By Pierre Ferron, Director of Wealth Engineering atAltaroc Wealth
Article 2 - Income Tax Scale and Replacement Income
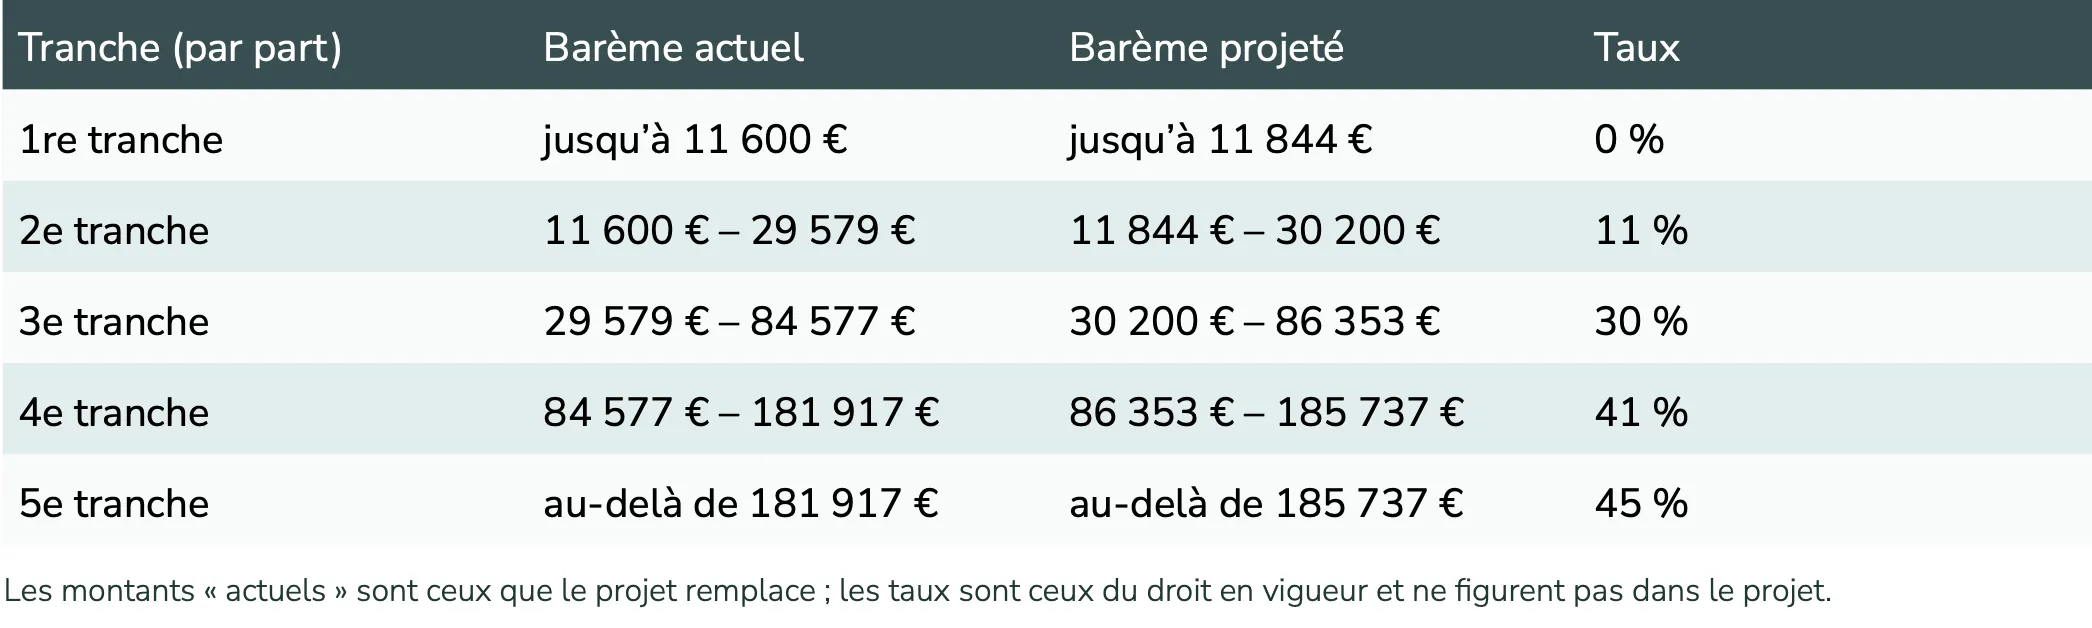
Income Tax Brackets
The article increases the tax bracket limits and associated thresholds by 2.1% (based on the 2025–2026 inflation forecast, excluding tobacco), for tax due in 2027 on income earned in 2026. The tax rates remain unchanged; they are listed below.
Severance Pay
The income tax exemption threshold will be unified and set at the annual social security threshold ( €48,060 in 2026), replacing the current thresholds based on a multiple of earnings.
Article 3 - 10% Reduction on Retirement Pensions
The cap on the 10% deduction applicable to retirement pensions is reduced from €4,439 to €3,000 ( Art. 158, 5, a). The €4,439 cap remains in effect for alimony and disability benefits. In practical terms, the deduction limit is reached once retirement pension income reaches €30,000.
Article 4 - Temporary Reduction in Gift Taxes
Gifts of money in full ownership made from January 1 through June 30, 2027, would be subject to a flat rate of 6 percent, up to a limit of €100,000 per donor and per donee. The rate is reduced to 5% if the donee contributes at least 1.1% of the funds received to an organization that assists people in need or victims of domestic violence (Art. 200, 1 ter of the General Tax Code); in which case this payment would not qualify for the tax reduction under Article 200 (75% for such organizations, up to a limit of €2,000 in donations). The donee must be a child, grandchild, great-grandchild, or, failing that, a nephew or niece, who is of legal age or emancipated and under 50 years of age. The gift must be reported or registered within one month. During the same period, the exemption under Article 790 G (family gifts, known as “Sarkozy gifts”) would be raised from €31,865 to €50,000.
Article 5 - Reallocation of the Contribution-Transfer (Art. 150-0 B ter of the General Tax Code)
When a contributor contributes securities to a corporation, the tax on the capital gain from the contribution is deferred. This tax becomes due if the contributed securities are sold within 3 years of the contribution, unless 70% of the proceeds from the sale are reinvested in an eligible business within 3 years. In this case, the assets acquired through reinvestment must be held for 5 years. The deferred tax is currently settled upon the contributor’s death. In the case of a gift, it is transferred to the donee and then settled after the securities have been held for 6 years (11 years if reinvested through a fund).
Project Measures
The deferral expires in the event of a transfer without consideration (gift or inheritance): income tax and social security contributions become due.The exit tax ( Art. 167 bis) follows the same logic. Payment in installments over five years is possible upon request, subject to the provision of collateral (new Art. 1681 G). The provision applies to transfers made on or after October 1, 2026. As the text currently stands, gifts made prior to that date continue to be subject to the tax (transfer to the donee, followed by retention). The tax would be owed by the donor or the decedent, whose estate will bear the tax liability. It should be noted that this measure applies to all capital gains arising from contributions, regardless of whether a sale occurred within the three-year period.
Article 6 - Changes to the Life Insurance Model
The new Article L. 131-1-3 of the Insurance Code prohibits the placement, in dedicated unit-linked funds (used to support a single policy or a closed group of policies), of assets issued, guaranteed, or owed by the policyholder, the insured, the beneficiary, their immediate family, or entities they control.
The tax treatment of life insurance (surrender and death benefits) would also be subject to three cumulative conditions:
• premiums paid in cash as of October 1, 2026;
• unit-linked assets similar to those listed in the Insurance Code;
• No assets of the policyholder or their circle are backed by the policy (see below).
Otherwise, the surrender value will no longer qualify for the reduced flat-rate levy of 7.5% (for policies with a term of eight years or more, with premiums up to €150,000). The proceeds would then, it appears, be subject to the 12.8% rate, as the text does not specify otherwise. Upon death, the amounts paid out would be subject to estate tax according to the degree of kinship (Art. 757 B, II bis), thereby losing the specific provisions of Article 990-I (a €152,500 exemption and rates of 20% and 31.25% on death benefits exceeding €852,500).
Effective Date
• Contracts entered into on or after October 1, 2026: effective immediately.
• Existing contracts: The prohibition under the Insurance Code takes effect on July 1, 2027. For income tax purposes, the tax rules apply as of October 1, 2026, but only to proceeds from premiums paid on or after that date.
• Deaths on or after July 1, 2027: Compliance is assessed as of the date of death and applies to all amounts due, including past premiums. However, the cash payment requirement applies only to premiums paid on or after October 1, 2026.
Article 7 - Non-Commercial Furnished Rental (LMNP)
For non-professional furnished rentals, the depreciation of the premises would now be capped. Landlords operating under the professional rental regime (LMP) are not affected.
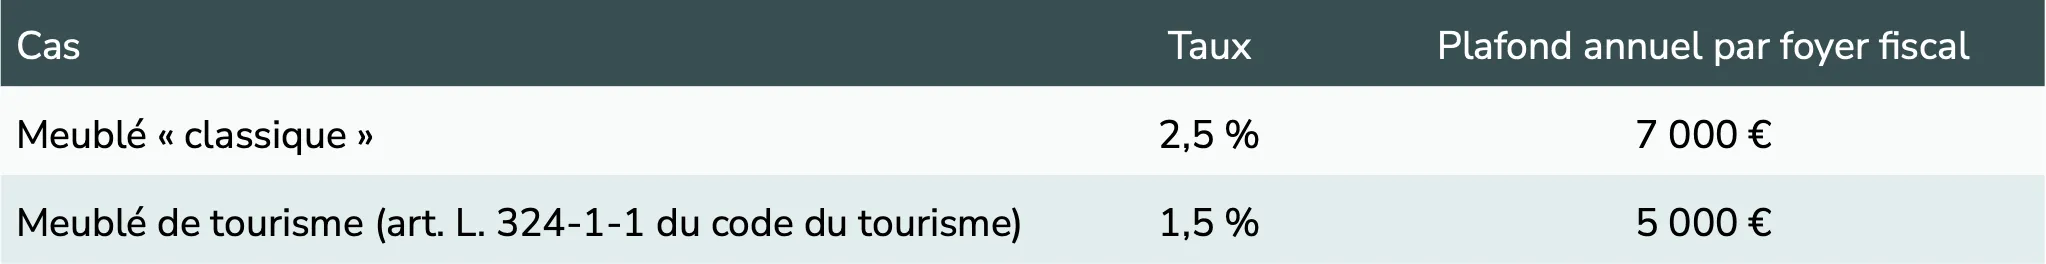
The cap is calculated per tax household, across all types of property, and applies to “direct or indirect” rentals.
Article 10 - The “Papin” Pact – Support for Business Takeovers
Employee Buyout
A seller who claims retirement benefits is entitled to a fixed deduction on their capital gain (Art. 150-0 D ter, II ter), which is increased from €500,000 to €1,000,000 when the seller transfers the business to one or more employees, or to a company owned exclusively by employees. At least one employee-buyer must provide proof of five years of employment over the past ten years, commit to holding a management position for five years, and retain the shares for the same period.
Effective Date
Sales made between January 1, 2027, and December 31, 2029.
Disclaimer
This document has been prepared by Altaroc Wealth for informational purposes only. It does not constitute a contractual document and, on its own, does not constitute personalized legal, tax, accounting, or wealth management advice or consultation. The information presented is of a general nature and has not been prepared with regard to the personal, financial, or tax situation; knowledge and experience; financial circumstances; objectives; needs; or risk profile of any specific recipient.
This document does not constitute an offer, a solicitation, or—unless expressly stated otherwise—a personalized recommendation to purchase, subscribe to, sell, or hold a financial instrument, an insurance product, or any other financial product or service.
Any decision regarding assets, finances, or investments must be evaluated in light of the specific circumstances of the individual concerned and, where applicable, based on the relevant contractual, precontractual, and regulatory documentation. The recipient is encouraged to review this documentation and, where appropriate, to seek their own legal, tax, accounting, or financial advice before making any decision.
This document was prepared based on information thatAltaroc Wealth considers reliable as of the date of its preparation. Altaroc Wealth strives to ensure that the information provided is accurate and up-to-date but cannot guarantee its completeness. This information is subject to change and may be modified without notice. Information provided by third parties remains the responsibility of their authors and is identified as such where appropriate.
All investments involve risks, including the risk of partial or total loss of the principal invested. The value of an investment and the income it may generate may rise or fall. Past performance is not indicative of future results and is not consistent over time. The risks specific to each investment are described in its regulatory and contractual documentation, which should be reviewed before making any investment decision.
Altaroc Wealth shall not be held liable for any decision made solely on the basis of the general information contained in this document, subject to its liabilities under applicable laws and regulations.
This document is intended exclusively for its recipient(s). Unless otherwise required by law or regulation, it may not be reproduced, distributed, or disclosed, in whole or in part, to third parties without the prior authorization ofAltaroc Wealth.
© Altaroc Wealth - All rights reserved.
Legal Notice
ALTAROC WEALTH | Simplified joint-stock company with a single shareholder, with capital of €1,000 | Paris Trade and Companies Register No. 107 970 162 | Registered office: 61 rue des Belles Feuilles, 75116 Paris | Email: contact-wealth@altaroc.pe | Website: www.altaroc.pe.
A consulting firm specializing in organizational and wealth management consulting and wealth engineering, registered with ORIAS under No. 26011661 (www.orias.fr) as an insurance or reinsurance broker (COA), engaged in brokerage activities
without accepting third-party funds. Member of CNCEF Assurance, a professional association accredited by the Prudential Supervision and Resolution Authority (ACPR) for its insurance brokerage activities.
Professional Liability Insurance with MMA IARD Assurances Mutuelles / MMA IARD, policy No. 113.520.558, policyholder No. 036104, and with Liberty Mutual Insurance Europe SE, ORIA Finance & Patrimoine contract No. LMIEORIA001 26/OC100002191, whose French branch is located at 42 rue Washington, 75008 Paris, registered with the Paris Trade and Companies Register under No. 408 774 610.